Is QROPS the same as repatriating pension cash?
Quick answer: no. A QROPS transaction is a pension-to-pension transfer to a qualifying overseas scheme. Cash repatriation means first taking benefits from the UK pension and then sending money to India. The tax point, access to funds, investment wrapper, transfer charges and advice requirements can therefore be very different.
Neither route is automatically best. The useful comparison is the net amount, restrictions and risks under your own scheme and residency position, not a claim that one route always preserves 100% of the fund.
How does direct pension cash repatriation work?
With cash repatriation, the UK pension pays benefits to you. You then convert or transfer the resulting cash to an Indian account. HMRC states that a person can usually take up to 25% of a pension tax-free, subject to the applicable lump-sum allowance; the remaining taxable amount is normally treated as income. See the official UK pension tax-free allowance guidance.
A large one-year withdrawal can push taxable income into higher bands. A provider may also use a temporary or emergency tax code on an initial flexible payment. The amount withheld is not always the final liability, and a repayment process may be available. Non-UK residence and treaty relief can change the analysis, so obtain a calculation before requesting payment.
Costs to include in a cash-out illustration
- UK income tax expected and tax initially withheld.
- Provider dealing, closure or withdrawal charges.
- The bank or foreign-exchange provider's fee and GBP-INR spread.
- Indian tax, reporting and foreign-tax-credit treatment.
- The investment return and protection lost when money leaves the pension wrapper.
Ask for an executable exchange-rate quote rather than relying on an advertised mid-market rate. A fixed claim that conversion always costs 3% to 5% is not reliable because pricing varies by provider, amount and service.
How does a QROPS transfer work?
In a QROPS transfer, the UK scheme sends pension rights to a receiving scheme that meets HMRC's requirements. The funds remain within a pension structure rather than becoming immediately spendable bank cash. The receiving scheme controls permitted investments, withdrawals, charges and death benefits.
A transfer can still trigger a 25% Overseas Transfer Charge unless an exemption applies. Residence at transfer, the location and type of receiving scheme, and later changes during the relevant period matter. Read HMRC's current overseas pension transfer guidance and verify the receiving scheme against the live ROPS notification list.
QROPS status is not a recommendation
Appearance on HMRC's list concerns the scheme's notification status; it does not mean HMRC has approved the scheme's investments, fees or suitability. Confirm regulation, custody, benefit rules and advice protections independently.
QROPS versus cash repatriation: what changes?
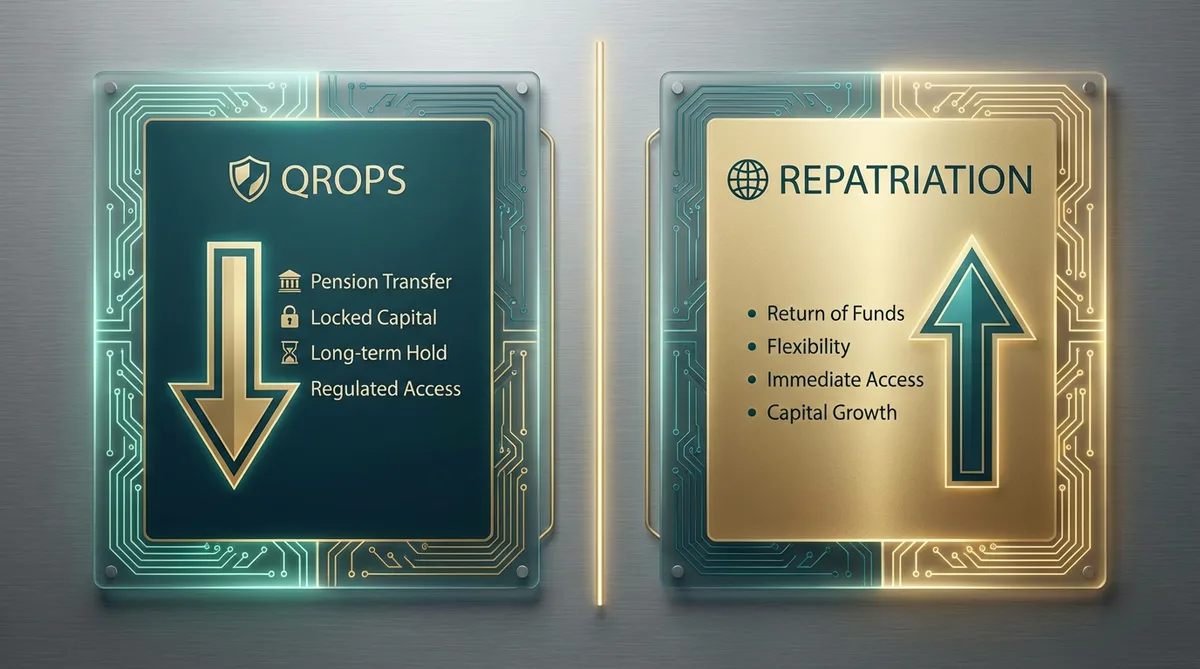
- Tax event: cash withdrawal can create immediate pension income; a transfer has separate overseas-transfer tax rules.
- Access: cash is liquid after payment; QROPS benefits remain subject to pension and scheme restrictions.
- Currency: cash can be converted immediately or in stages; a QROPS may offer GBP, INR or other holdings depending on its rules.
- Charges: compare one-off and ongoing advice, platform, fund, custody, withdrawal and FX costs over several years.
- Guarantees: transferring may surrender safeguarded benefits, guarantees or favourable UK scheme pricing.
- Beneficiaries: nomination and death-benefit choices differ by scheme and need a separate tax review.
- Reversibility: once a pension has paid out or completed a transfer, restoring the previous arrangement may be impossible.
Worked comparison framework for a £100,000 pension
Do not treat the following as a quote. Use £100,000 as a common starting value and obtain four provider-specific figures:
- Keep in the UK: project annual drawdown, UK charges, Indian reporting and currency conversion as spending occurs.
- Withdraw cash: estimate the tax-free amount, taxable payment, initial withholding, final UK liability, Indian treatment and FX proceeds.
- Transfer to QROPS: show any Overseas Transfer Charge, transfer advice, receiving fees, investments and future withdrawal tax.
- Stress test: repeat the comparison with lower returns, higher fees and a weaker GBP-INR rate.
Our QROPS calculator can organise an initial comparison, but a regulated transfer analysis must use your scheme's actual benefits and current tax assumptions.
When might cash repatriation deserve consideration?
Cash may merit analysis where benefits are already accessible, liquidity is genuinely required, the pot is modest, and the combined tax and loss of pension protection are understood. Small-pot and serious-ill-health rules may also affect some members. It is still important to compare staged withdrawals rather than assuming the entire fund must be taken in one tax year.
When might QROPS deserve consideration?
A QROPS may merit analysis where the pension is transferable, the member expects long-term overseas residence, the receiving scheme fits the desired benefits and currency, and the tax and fee model remains competitive after stress testing. Defined-benefit and other safeguarded arrangements require particular care because valuable guarantees can be lost.
Questions to answer before choosing either route
- Can the scheme legally transfer, and does it contain safeguarded benefits?
- What are your UK and Indian residence statuses on the transaction date?
- What tax will be withheld initially and what is the expected final liability?
- Does the Overseas Transfer Charge apply now or after a later change?
- What will both routes cost over one, five and ten years?
- Which currency will fund retirement spending, and when must conversion occur?
- What happens on death, divorce, relocation or a need for emergency cash?
Compare like with like
Build a written QROPS versus cash-out model
Bring your latest pension statement, residence timeline and expected spending. We will help frame a provider-specific comparison for review with regulated pension and tax professionals.
Final takeaway
Cash repatriation and QROPS solve different problems. Compare final tax, ongoing costs, access, guarantees, currency and beneficiary outcomes before acting. This article provides general information and is not personalised pension, tax or investment advice.